Table of Contents
- Start With a Complete Rental Application Checklist
- Tenant Screening Red Flags That Signal Risk
- How to Verify Tenant Income and Employment
- How to Verify Rental History and Landlord References
- Credit Reports, Background Checks, and Public Records
- Fair Housing Compliance and Adverse Action Procedures
- Risk Mitigation After Approval and Conclusion
- Frequently Asked Questions
Last Updated: October 14, 2026
Start With a Complete Rental Application Checklist
Identifying high risk tenants effectively starts before you ever run a report. It starts with a written process that treats every applicant the same way. At MacData, we have spent over a decade helping landlords and property managers across Volusia County screen applicants. A complete rental application checklist is your first line of defense.
Documents to Collect From Every Applicant
Ask for the same documents from every single person who applies, no exceptions. A consistent rental application checklist looks like this:
- Government-issued photo ID
- Completed rental application with signature
- Proof of income (recent pay stubs or bank statements)
- Employer contact information
- Two to three landlord references with phone numbers
- Signed consent for a screening report
That last item matters more than most landlords realize. Under the Fair Credit Reporting Act, you need written permission before pulling a credit report or background check (the FTC). Get it in writing, every time.
Written Screening Criteria and Consistent Evaluation
Write down your screening criteria before you advertise the unit. Put them in plain language: minimum credit score, income-to-rent ratio, how you handle eviction records, and what you count as a red flag.
Consistent evaluation does two things. It protects you from fair housing complaints, and it gives you a clear paper trail if an applicant challenges your rental decision.
Keep your written criteria in the same document as your application. When an applicant asks why they were denied, you can point to the exact rule, which is the fastest way to shut down a discrimination claim.
Tenant Screening Red Flags That Signal Risk
Tenant screening red flags fall into two groups: what the paperwork says, and how the applicant behaves. Both matter. The paperwork tells you about the past. The behavior tells you about the present.
Watch for these warning signs during the application review:
- Refuses to provide a Social Security number or ID
- Income claims that do not match the pay stubs
- Vague or evasive answers about current or past landlords
- A rental history with unexplained gaps
- Pressure to skip the screening step “just this once”
A single red flag does not automatically mean denial. A pattern of them usually does. The goal is risk assessment, not finding one perfect applicant.
Application Fraud and Identity Verification
Application fraud is more common than most small landlords expect. Someone uses a fake pay stub, a borrowed identity, or a “landlord reference” who is actually a friend. Identity verification is your defense.
Match the name on the ID to the name on the application. Check that the photo looks like the person in front of you. Call the employer and the landlord references yourself rather than trusting a number the applicant provided.
How to Verify Tenant Income and Employment
How to verify tenant income comes down to one rule: confirm the number, do not trust it. An applicant can type any figure into a rental application. Your job is to prove it against a real document.
Ask for the last two to three pay stubs and a recent bank statement. Then call the employer to confirm the job title, start date, and pay rate.
Income-to-Rent Ratio and Stable Income
The income-to-rent ratio is the most useful single number in tenant screening. Most property managers look for monthly income that is at least three times the rent.
Stable income matters as much as the total. A applicant who has held the same job for three years is a safer bet than one who just started a higher-paying role last month.
How to Verify Rental History and Landlord References
How to verify rental history means going past the names on the form. Anyone can list three references. The work is in confirming they are real and that they tell the truth.
Call each landlord reference and ask specific questions:
- Did the tenant pay rent on time?
- Did they give proper notice before moving out?
- Were there complaints from neighbors?
- Would you rent to them again?
That last question is the one that matters. A hesitant pause says more than a polished answer.
Payment History and Eviction Records
Payment history is the clearest predictor of future tenant behavior. Late payments in a screening report are a yellow flag. A pattern of missed payments is a red one.
Eviction records deserve careful handling. Many evictions never make it into public records, and some records are sealed or too old to use. Check your state and local rules on how far back you can look and what you are allowed to consider.
Credit Reports, Background Checks, and Public Records
A screening report pulls three things together: a credit report, a background check, and public records. The credit report shows how someone handles money. The background check covers criminal records.
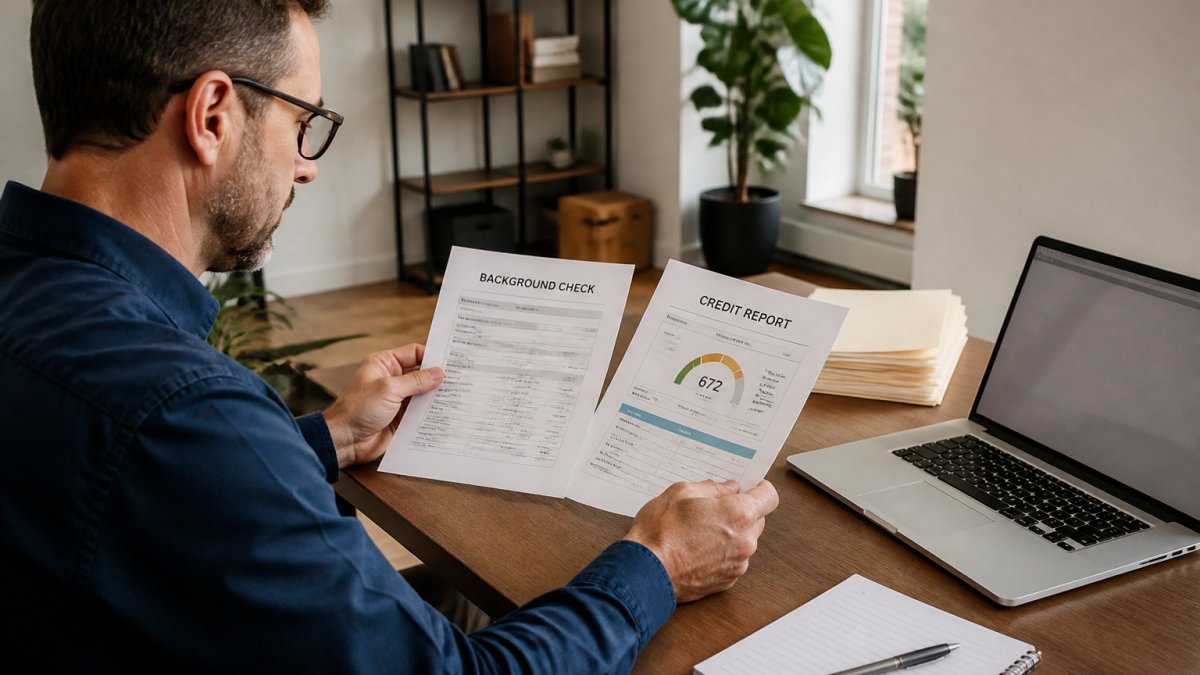
Credit score and credit history are useful, but they are not the whole story. A low score from medical debt is very different from a low score from unpaid rent.
Contextual Review: Avoiding False Positives
Contextual review means looking at the whole person, not one line on a report. This is where a lot of landlords get it wrong.
Ask three questions before you deny anyone:
- How old is the record or the missed payment?
- What was the reason behind it?
- Does it relate to the person’s ability to pay rent and follow a lease?
A single old charge or a rough financial year does not predict a bad tenant. The HUD guidance on fair housing and criminal records explains why blanket bans on anyone with a record can create legal exposure.
Do not deny an applicant based on an arrest that never led to a conviction. Many screening databases mix arrests and convictions together, and using an arrest alone as a reason to reject can violate fair housing rules and state law.
Fair Housing Compliance and Adverse Action Procedures
Fair housing compliance is not optional, and it is where small landlords get sued most often. The Fair Housing Act bars you from denying an applicant based on race, color, national origin, religion, sex, familial status, or disability. Many states and cities add protected categories on top of the federal list, and those local rules are where the practical risk lives.
Know Which Local Rules Apply to You
Screening rules vary more by location than most landlords realize. Before you write your criteria, check the rules in the jurisdiction where the rental sits, not where you live. A few categories are worth checking every time:
- Source of income. A growing number of states and cities prohibit refusing an applicant because their rent would be paid partly or fully by a housing voucher or other lawful subsidy. In those places, a blanket “no vouchers” rule is a fair housing violation, not a preference.
- Criminal record lookback. Some jurisdictions limit how far back a landlord may consider a criminal record, and some restrict considering arrests that never led to a conviction. A record that is usable in one city may be off-limits in the next one over.
- Eviction record lookback. Rules on how far back eviction filings may be considered, and whether sealed or dismissed cases can be used, differ by state and sometimes by court.
- Credit and rental history. A few jurisdictions restrict using credit history or a lack of rental history as an automatic disqualifier.
Because these rules change, the safe habit is to confirm your criteria against current local law at least once a year and any time you change markets. A criteria sheet that was compliant two years ago may not be today.
Apply Criteria Consistently to Every Applicant
Consistency is the core of fair housing compliance. The same written criteria, applied in the same order, to every applicant, is what separates a defensible decision from a discriminatory one. That means:
- Advertise the unit the same way to everyone, with the same rent, deposit, and terms
- Give every applicant the same application and the same document requests
- Run the same screening steps in the same sequence
- Score every applicant against the same rubric before making a decision
- Keep the application, the screening report, your notes, and the decision in one file
If you cannot explain your criteria out loud, they are not written clearly enough. Write them down, date them, and keep a copy with the application.
Adverse Action Procedures When a Report Drives the Denial
Adverse action procedures are the steps you must take when you deny an applicant based in whole or in part on a screening report. Get them right:
- Send a written notice of adverse action
- Include the name, address, and phone number of the screening company that provided the report
- Tell the applicant they have the right to a free copy of the report
- Explain their right to dispute inaccurate information with the screening company
- State that the screening company did not make the decision and cannot give the reasons for it
The FTC rules on adverse action and background reports spell out exactly what that notice must contain. Skipping it is one of the most common and most expensive mistakes in property management.
A denial that is not based on a screening report, for example a failed income-to-rent ratio you calculated yourself from documents the applicant provided, generally does not trigger the same adverse action notice.
Write your criteria, check them against local rules, score every applicant the same way, and send an adverse action notice whenever a screening report plays a role in a denial. That four-step workflow is what holds up if anyone questions your rental decision.
A repeatable scoring rubric keeps you consistent. Score each applicant on the same factors, credit, income, rental history, and references, then compare the totals. This is the workflow that holds up if anyone questions your rental decision.
Risk Mitigation After Approval and Conclusion
Approval is not the finish line. A tenant can pass screening and still create problems later. The landlords who stay protected keep watching after the lease is signed.
A few habits cut your risk after move-in:
- Document the unit’s condition with dated photos before move-in
- Set clear, written lease terms and review them with the tenant
- Track rent payments and act fast on the first late payment
- Schedule periodic check-ins and unit inspections
The biggest challenge in tenant screening is doing it the same way every time, for every applicant, without cutting corners. That is where a partner like MacData helps. We offer FCRA-compliant tenant screening with fast, secure reporting and one easy-to-use system for all your screening needs.
Frequently Asked Questions
What are the biggest red flags for high risk tenants?
Common red flags include a credit score well below your published minimum, an income-to-rent ratio under 2.5x, frequent late payments or missed payments in a credit report, eviction filings on record, a rental history with gaps or unpaid balances, and landlord references that are unreachable or give evasive answers. Application fraud, such as altered pay stubs or mismatched identity documents, is another strong warning sign. Treat any single red flag as a prompt for deeper verification rather than an automatic denial.
How can landlords verify a tenant’s income and rental history?
For income, request recent pay stubs, employer contact information, and bank statements, then confirm employment directly with the employer’s HR or payroll department. Self-employed applicants can provide tax returns, 1099s, and profit-and-loss statements. For rental history, contact current and previous landlords by phone, ask about on-time rent payments, lease compliance, property condition, and whether the tenant gave proper notice. Cross-check dates and addresses against the application to catch inconsistencies.
What should landlords do if a tenant screening report raises concerns?
First, apply your written screening criteria consistently so every applicant is judged the same way. If a report shows something like an old eviction or a collection account, review it in context: how recent, how severe, and does the applicant’s explanation hold up. You can request additional documentation or a co-signer. If you decide to deny, send a compliant adverse action notice that identifies the screening company and explains the applicant’s right to dispute inaccurate information.
How can landlords screen applicants fairly and consistently?
Publish your screening criteria in advance, covering minimum credit score, income-to-rent ratio, rental history, and background check standards. Apply those criteria to every applicant in the same order and keep written records of each decision. Follow fair housing rules by never basing decisions on race, color, religion, sex, national origin, familial status, or disability. A consistent, documented process reduces legal exposure and makes it easier to defend a rental decision if a complaint arises.